-
Home
Home
-
List or Buy with Joy Residential
List or Buy with Joy Residential
-
Testimonials
Testimonials
-
Contact Us
Contact Us
-
My Search Portal
My Search Portal
Home
List or Buy with Joy Residential
Testimonials
Contact Us
My Search Portal
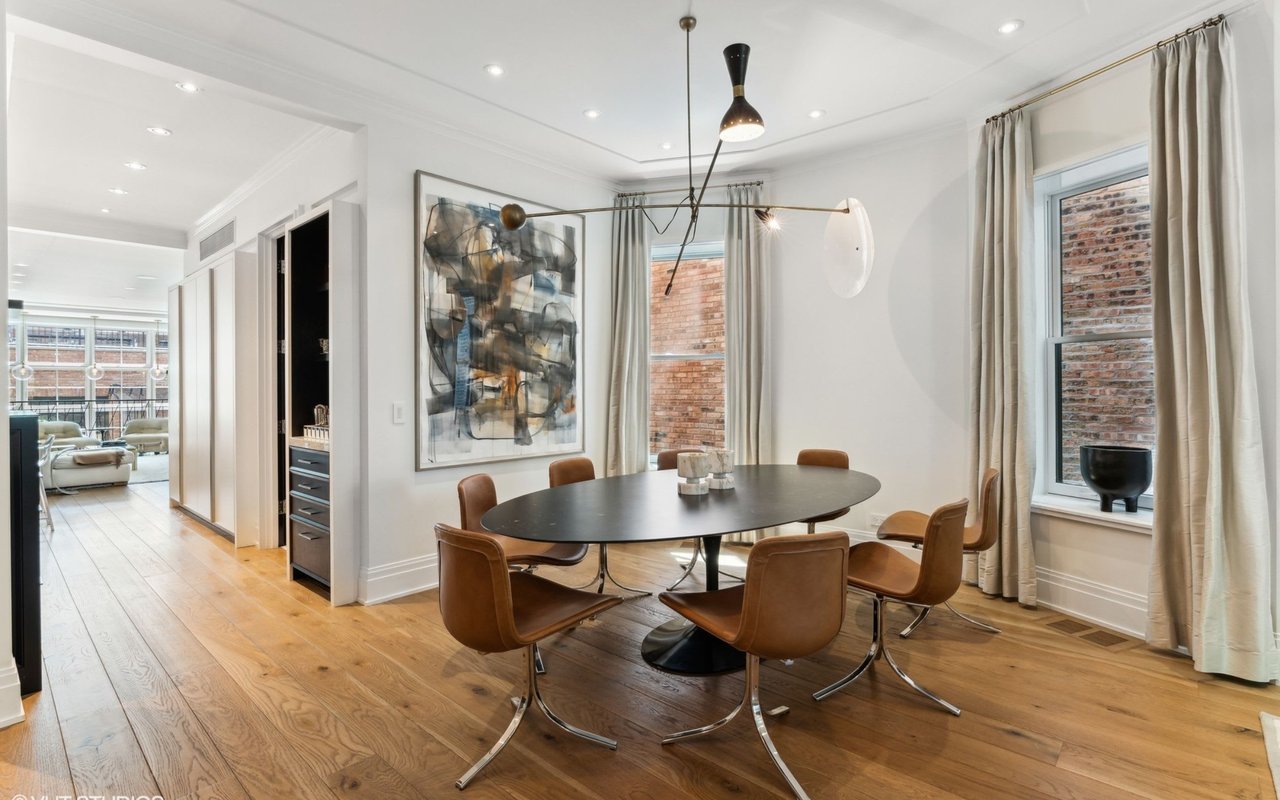
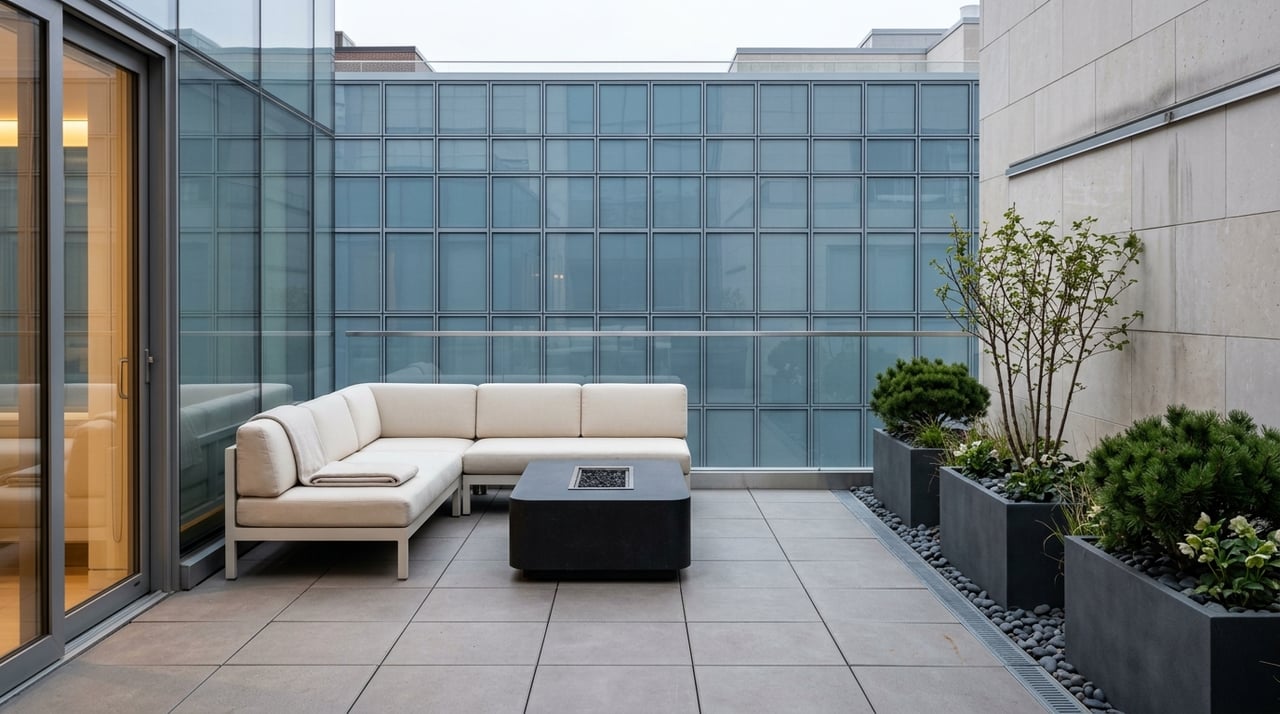
Are you dreaming about city life in Chicago and weekends in Park City? You are not alone, but buying in both places works best when you treat the decision as one coordinated plan, not two separate purchases. The right setup can help you avoid surprises with taxes, financing, and rental rules while keeping your long-term lifestyle front and center. Let’s dive in.
Owning a home in Chicago and a retreat in Park City can be a smart lifestyle move, but the two properties usually do not play the same role. In most cases, your Chicago home will be your principal residence, while your Park City property will be a second home. That distinction affects how each property is taxed, financed, and used.
It also matters because the two markets are moving differently. In March 2026, Chicago had 2,981 homes for sale, down 28.8% from the year before, with a median sales price of $409,200 and homes selling in 32 days on average. In Park City, Q1 2026 brought 529 transactions and $1.195 billion in sales volume, with single-family homes outperforming condos.
When two markets behave differently, your timing and property choices matter more. A coordinated approach helps you decide where to move first, which property type fits your goals, and how to structure each purchase with fewer last-minute issues.
Before you look at finishes, views, or floor plans, decide which home will truly be your principal residence. This is the foundation for the rest of your plan because tax benefits and occupancy rules follow actual use, not just what you would prefer on paper.
In Cook County, the Homeowner Exemption is available when you occupy the home as your principal residence. Once approved, it renews automatically, and the Cook County Assessor says it saves homeowners an average of about $950 per year. That makes early planning especially important if your Chicago property will be your full-time home.
Utah handles this differently but just as strictly. The Primary Residential Exemption removes 45% of fair market value from taxation for a qualifying primary residence, but a Park City retreat usually will not qualify unless it truly becomes your principal home. Utah also notes that a primary residence does not include transient-use property or condominiums used in rental pools.
For part-year use, Utah allows the exemption only if the home is used as a primary residence for 183 or more consecutive calendar days in the year. In other words, you generally cannot treat both homes as primary residences at the same time. Your occupancy pattern needs to match the classification.
Chicago transfers come with multiple layers of transfer tax, and those costs should be built into your budget from the start. Illinois charges $0.50 per $500 of value, Cook County charges $0.25 per $500, and the City of Chicago charges $3.75 per $500 to the transferee plus a $1.50 per $500 CTA portion to the transferor.
These rules can become more nuanced when a property is held in trust. Chicago's ordinance also applies to transfers of beneficial interest, not just deed transfers. If you are considering a trust-based ownership structure, it is wise to review that plan before you are under contract.
Cook County also builds residential taxes from assessed value, equalization, exemptions, and local levies. That means your property classification is not something to leave until closing week. Confirming how the home will be treated can help you avoid confusion after the sale closes.
Second-home financing comes with its own boundaries, especially for a Park City purchase. Freddie Mac's current second-home guidance requires the mortgage to be secured by a one-unit property, and the borrower must occupy the home for some part of the year while keeping it primarily available for personal use.
Short-term rentals may be possible in some cases, but there are limits. Freddie Mac says a second home cannot be in a rental pool or subject to a management arrangement that controls occupancy or shares revenue with a developer or another party. That can affect certain resort-style ownership models.
Freddie Mac also says rental income from a borrower’s second home may not be used as stable monthly income. If your purchase depends on offsetting costs with rental revenue, that issue should be reviewed before you begin writing offers.
The practical takeaway is simple. If you want cleaner second-home financing, a straightforward one-unit Park City property with personal-use flexibility is often easier to align with lender rules than a property tied to mandatory rental participation.
In Park City, property type is not just a style decision. It can affect financing, future use, and resale flexibility. Q1 2026 data showed a split market, with single-family homes gaining strength while condos saw sharper declines in both unit sales and volume.
That does not mean a condo is the wrong choice. It means your intended use should drive the decision. If your focus is personal retreat, lock-and-leave convenience, occasional stays, or easier maintenance, a condo may still fit your goals.
If you want more control over occupancy, a different ownership feel, or a property type that has recently shown stronger market performance, a single-family home may deserve a closer look. In a segmented market like Park City, property-level differences matter more than broad averages.
If there is any chance you will rent your Park City home, even occasionally, confirm the local rules before moving forward. In Park City, a nightly rental license is required for rentals under 30 days if zoning allows that use.
For long-term rentals over 30 days, the city states that these are licensed and regulated through Summit County when the property is within the county’s jurisdiction. This is why two homes that look similar on a listing sheet can have very different use potential once zoning and licensing are reviewed.
This step matters for more than compliance. It also helps you avoid buying a property that does not match your real plans, whether that means personal use only, limited rental flexibility, or a future conversion to a longer-term rental.
Chicago’s spring 2026 market showed lower inventory and faster sales than the year before. With inventory down 28.8% and average days on market down to 32, buyers looking for a primary home in Chicago should be prepared to act decisively when the right property appears.
Park City requires a different kind of timing strategy. Because the market is segmented and property type matters so much, the process often benefits from careful filtering before you tour. Instead of looking broadly, you may want to narrow by intended use, ownership structure, and whether rental flexibility is important.
When you are buying in both places, sequencing matters too. Some buyers start with the Chicago primary residence to secure their principal-home base. Others begin with Park City if a rare property appears and the financing path is already clear.
If you want to make this process more manageable, start with a clear framework:
This kind of planning helps turn a complex idea into a cleaner decision. It also gives you a stronger position when the right opportunity appears in either market.
Buying across Chicago and Park City is not just about finding two beautiful homes. It is about understanding how two different local systems interact with your goals. Tax treatment, transfer costs, occupancy rules, financing standards, and rental restrictions all need to work together.
That is where founder-led, cross-market guidance can make the process feel calmer and more focused. When you work with someone who understands both the city and resort side of the equation, you can build a plan around how you actually want to live, not just around what looks good online.
If you are considering a Chicago primary home and a Park City retreat, a private strategy conversation can help you define the right order, the right property type, and the right ownership structure before the first contract is signed. To start that conversation, connect with Joy Residential.
Browse active listings in the area or contact us for off-market listings.
Have an expert help you find out what your home is really worth.